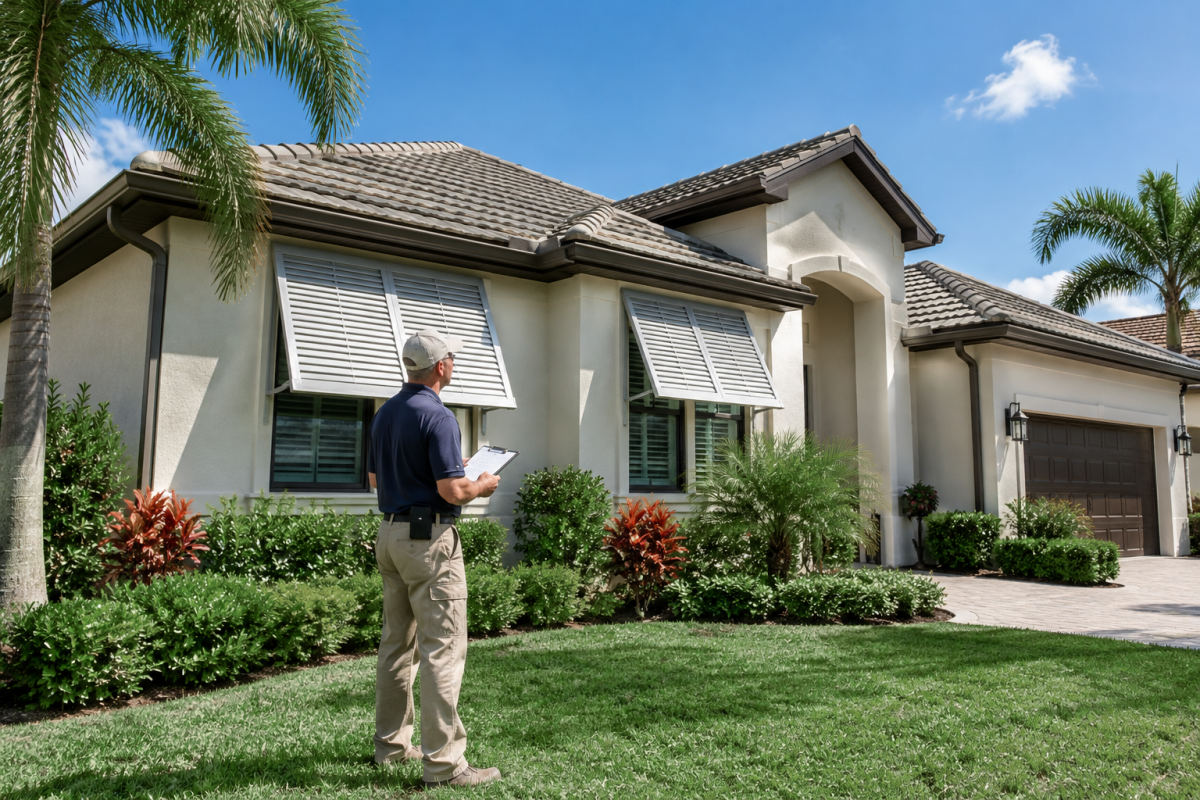
Florida’s My Safe Florida Home (MSFH) Program can help eligible owners pay for upgrades that make a home more resistant to hurricane damage. The important thing to understand upfront: this is a staged program, not a one-click rebate. A free wind-mitigation inspection comes first; a separate grant application comes later, and work generally must wait until that grant is approved.
Who can start with a free inspection?
The program is designed for owner-occupied Florida homes. In general, the property must be a site-built, single-family home on its own parcel, and the owner must have a homestead exemption. Condos, co-ops, mobile and manufactured homes, multifamily properties, rentals and vacation homes are not eligible for the free inspection.
Begin by creating an account in the MSFH applicant portal and completing the required Prioritization Questionnaire. That questionnaire uses household income and age information to place applicants in a priority group. Group placement controls when an inspection or grant application becomes available, so submitting the questionnaire does not mean an inspection is instantly scheduled. Keep an eye on both the portal and the email account connected to it.
Grant eligibility: the key rules
Getting an inspection does not automatically qualify a homeowner for grant money. For a hurricane-mitigation grant, the home must have received an MSFH initial inspection within the past 24 months, have an insured dwelling value of $700,000 or less, and have been built before January 1, 2008, according to the county property appraiser record.
You will also need a current homeowners insurance declarations page showing the property address, policyholder, effective dates and Coverage A dwelling value. The project must use a properly licensed Florida contractor, and the program will ask for that contractor’s identifying and license information. Most importantly, the work must be recommended in the initial inspection report and later observed in the final MSFH inspection.
Eligible work can include approved opening protection, roof-to-wall attachments, roof-deck attachment improvements and secondary water resistance. The inspection report—not a contractor’s sales proposal—sets the list of improvements that can be funded.
From inspection to grant payment
- Create your portal account and complete the questionnaire. Wait for your inspection-group access, then submit the inspection application.
- Complete the free initial inspection. Review the report carefully when it arrives. If it contains no recommended improvements, there is no grant project to pursue.
- Opt in for the grant phase. Eligible homeowners indicate interest in a grant, are sorted into a grant group and receive access when their application window opens and funding permits.
- Apply before construction starts. Submit the insurance documentation, select the report-recommended work and identify your intended contractor. Do not start the job before written grant approval.
- Finish the approved project, then request the final inspection. Local building permits and inspections are separate from the MSFH final inspection, so make sure both are handled where required.
- Submit the Draw Request. After the final report is uploaded, send the required invoices, payment records, insurance-discount documentation and disbursement details through the portal.
How the 2-to-1 matching grant works
The standard matching grant reimburses up to two-thirds of the approved project cost, with a maximum state contribution of $10,000. Put simply, the state contribution is $2 for every $1 the homeowner contributes. A $9,000 eligible project could produce a $6,000 reimbursement after completion, leaving a $3,000 homeowner share. On a $15,000 project, the state share reaches the $10,000 cap and the owner pays the remaining $5,000.
Matching grants are reimbursement-based: homeowners need to pay the contractor in full and upload the paid-in-full invoice with the Draw Request. Qualifying low-income homeowners may instead be eligible for a grant of up to $10,000 without a matching contribution or paid-in-full invoice requirement. Low-income status follows program income standards, so check the current portal requirements rather than relying on a general income estimate.
Common mistakes that can derail a case
- Starting work too soon. Work completed before grant approval is not eligible for payment, even if it appears in the inspection report.
- Assuming every upgrade is covered. Only initial-report recommendations that the final inspector can observe are payable.
- Uploading the wrong insurance proof. A declarations page should clearly show Coverage A, not merely the policy premium or liability limits.
- Choosing a contractor without checking the license. Verify the license is active and appropriate for the work before submitting the contractor information.
- Ignoring portal requests. A request for information must be answered within 60 days or the case can be withdrawn and closed.
- Waiting too long after approval. Request the final inspection within one year of approval, or request the available one-time six-month extension before that deadline. The practical maximum is 18 months.
- Using the final inspection too early. There is only one MSFH final inspection, so confirm the approved work is complete and properly installed before requesting it.
Practical takeaway: Save every portal email, read the initial report before signing a contract and treat grant approval—not the inspection—as the green light to begin work. Funding, group access and program documents can change, so confirm the current details in your MSFH portal before making financial commitments.